
The Fire Damage Restoration Process Explained
What reasons do insurers commonly give for denying fire claims, and how do you determine whether those reasons are supported by the policy and evidence?
There’s a multitude of reasons why a fire claim on a home could be denied by the insurance company.
One of the main reasons is arson. They could believe that the fire was intentionally set. By intentionally set, I mean intentionally set by the homeowner or at the direction of the homeowner.
If there’s a fire at your house and arson is alleged, it doesn’t mean that the claim will be denied. Typically, insurance companies deny arson claims when the fire is set by the insured or at the direction of the insured.
But let’s say there’s a fire that’s set intentionally by a trespasser or something like that while you’re out of town, or your house catches on fire because the house next to you was set on fire, for example, and it spreads to your house. That likely would be covered. So, just because there is arson involved- It doesn’t necessarily mean that it’s going to result in a denial.
It typically has to be set intentionally by the homeowner or at the direction of the homeowner.
Another reason fire claims get denied is because of things in the policy, like if the property’s been vacant for 60 days or 90 days and the house burns down, that could be a reason for the denial.
Another reason for the denial could be that the policy lapsed because the premiums weren’t paid. And there are other exclusions as well, but those are some of the more common ones when it comes to fire.
Related Article(s)
Insurance Lied to You? File Misrepresentation Claim
Texas Bad Faith Insurance Lawyer
We’ll Go Beyond to Get You Back
Get Compensated For Your Injuries & Damages! Call Us For A FREE Case Review. Call Us For A FREE & Confidential Case Review Today!

What documents would you review to decide whether a homeowner has grounds to challenge a denial?
So, in a fire case, the documents we would really want to look at are the fire marshal’s report to determine how the fire started.
So, if the fire marshal indicates that it’s an incendiary fire, that means it’s potentially arson, we obviously want to know whether that’s valid or not. Because, again, if it’s at the direction of the homeowner, that could be a real problem and could result in a denial of coverage.
If the fire marshal’s report indicates it’s undetermined, or it’s accidental, typically not a big deal. We then would want to look at the policy itself to determine what type of coverage is involved. We want to look at any estimates for the repairs, contractor estimates, to determine how much damage the fire caused, because that’s going to impact how much we can potentially claim.
We always want to look at things like photos and engineer reports if there are any. There’s a number of documents that could come into play in a fire claim.
What should a person do if they’ve had a fire to protect their claim?
Well, if you’ve had a fire, one of the first things you want to do is you go and take pictures of the damage. You also want to video it if you can, ’cause that often will help to document certain things. You want to start putting together a list of things that have been damaged or destroyed in the home because you will have multiple claims on the policy.
Understanding the Restoration Process
From an insurance claim perspective, what should homeowners prioritize immediately after a fire?
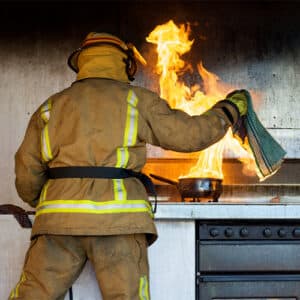 If you’ve had a fire, one of the first things you want to do is go and take pictures of the damage. You want to start putting together a list of things that have been damaged or destroyed in the home because you will have multiple claims on the policy.
First, you will have the claim for repair costs for the fire to fix the home. You’ll also have a content claim, which is what it sounds like. It’s how much of your contents you’ve lost and have to replace. You may also have an additional living expense claim, which means your house has caught on fire and you can’t live there while it’s being repaired, so there’s coverage for you to live somewhere else until the home is repaired.
So, you want to document that. You want to get the policy as well, to make sure you know what coverage you have. Then you immediately want to notify the insurance company. You want to put them on notice because that will trigger certain deadlines for them to come out and start to investigate the claim and hopefully pay the claim and assist you with your contractors and getting you back in your home and getting your home fixed.
If you’ve had a house fire in a kitchen and the rest of the house is okay, you don’t necessarily have to start pulling things out of the house and segregating things.
But if you’ve had a really bad fire that’s burned a large part of the property to the ground or something, you want to get an adjuster out there as quickly as possible. So, notify the insurance company immediately in the case of a fire. But they don’t have to come that day, but often if you do notify them early, they’ll want to get out there quickly to start investigating.
And, then once you’ve given them access to the home, the insurance adjuster will take pictures of the damage, and then they’ll start preparing an estimate. At that point, you can start to gather things that you want to take with you that haven’t been damaged if you have to move out of the home. Start making a list of things that are damaged that you’re going to want to submit to the insurance company to get that reimbursed.
So that’s mainly your personal items. Those can add up quite a bit, but you know, you do want to take pictures and video of everything, because things are going to get moved. Things will get moved around and ruined simply by the fire department ensuring the fire is out.
So, you want to document as much as you can by pictures and video the condition of the property. You also want to put the insurance company on notice so they can come out and do what they need to do in terms of investigating.
How can homeowners balance preventing additional damage with preserving evidence for the insurer’s investigation?
Yeah, so in a fire claim it’s often really hard to prevent additional damage because depending on how much damage the fire caused, there could be massive holes in the property that allow the elements to get in.
But one thing that people do is put a tarp over their roof, if there’s say a burned hole in the roof. You want to try as best you can to protect the inside of the property.
One of the main things you can do is hire a contractor pretty soon so they can start getting to work on the property.
Mitigation companies are often brought in to help remove certain items and get all the damaged stuff out of there. But also, the stuff that you can preserve, you want to get that out of the home too. If the home’s been compromised, if it’s open to the elements, you want to get the stuff that’s not damaged out, put that into storage so you can protect that as well. Just do your best to preserve your property.
It goes back to you just having to exercise common sense in terms of trying to protect the inside of the property as best you can.
If you’re able to do that with tarps, uh, I would recommend doing that or having… Often you can hire a contractor to come out there, and they will tarp it up and secure it for you. Um, that’s, that’s another avenue that you have potentially. Um, but it just, uh, fire is not a one-size-fits-all kind of thing.
It just depends on how much damage there is. Some homes are burned completely to the ground, so there’s not much you can do to protect the property in that situation.
But if you’ve got a really bad fire that’s burned a large part of the property to the ground or something – the main thing is you want to get an insurance adjuster out there as quickly as possible. Once you’ve given them access to the home, the insurance adjuster will take pictures of the damage, and then they’ll start preparing an estimate.
At that point, you can start to gather things that you want to take with you that haven’t been damaged if you have to move out of the home and start making a list of things that are damaged that you’re going to want to submit to the insurance company to get that reimbursed.
What should homeowners do if emergency protection or water removal is needed before the adjuster arrives?
“Sometimes insurance companies will send out water mitigation companies to attempt to dry out the house from all the water damage after a fire.
I’ve also seen insureds hire their own mitigation companies, like ServPro, to come out and do the best they can in terms of trying to dry the property out to prevent mold from growing. But it really depends on the level of damage.
Sometimes there’s so much fire damage that the home can’t really be repaired. I mean, it could be repaired, but it’s often a situation where if there’s so much damage, it can be considered a total loss. And if it’s considered a total loss, then the insurance company is required to pay the policy limit on the property.”

Removing Damaged Materials and Demolishing Unsafe Areas
 What evidence should homeowners preserve before damaged belongings or building materials are removed?
In a fire claim you don’t want to dispose of any of your items until you’ve taken pictures and video of the damaged items. Ideally, you want to give the insurance company an opportunity to send somebody out there to do their own investigation. To take pictures of your damaged content and as early as you can, you want to start making a list of your damaged items and make sure to take pictures of everything as well.
I do recommend NOT disposing of anything if possible until the insurance company has been given an opportunity to come out there and do an investigation and take pictures of those items.
How can disposing of items too early create problems with proving the loss or investigating the fire’s cause?
In a fire claim, you don’t want to dispose of any of your items until you’ve taken pictures and video of the damaged items and ideally, you want to give the insurance company an opportunity to send somebody out there to do their own investigation and take pictures of your damaged content.
As early as you can, you want to start making a list of your damaged items too. Make sure to take pictures of everything as well. And then I do recommend not disposing of anything if possible until the insurance company has been given an opportunity to come out there and do an investigation and take pictures of those items.
What can a homeowner do if the insurer and restoration contractor disagree about whether something can be repaired or must be replaced?
Okay. So, in terms of repair costs, oftentimes there will be some disagreement between the contractor and the insurance adjuster. Often, the disagreement is about how much something costs to repair and the charges that the contractor is putting into their estimate.
Typically the way that gets resolved is the contractor and the insurance company communicate and come up with some kind of compromise. So, the contractor knows, “Okay, I’m going to do this work, and the insurance company is going to pay X for it.”
That’s often how it gets resolved but there are times where the contractor will be brought in, do repairs, then their repair costs or actual invoices get submitted to the insurance company, and the insurance company sort of balks at it or says, “We’re not gonna pay $100,000, but we’ll pay $70,000.”
And then that ends up being a situation where you might have to get an attorney involved to bridge that gap to get enough money from the insurance co- company to cover all of the repair costs
What policy provisions should be reviewed when determining coverage for debris removal and demolition expenses?
Yeah, so there are specific policy provisions that apply to debris removal. They typically fall under the coverage for the dwelling. It’s typically in the policy that part of the dwelling limits will be used for debris removal and things of that nature, and that’s almost always covered because it’s directly related to the loss.
Addressing Smoke, Soot, and Contamination
How do you handle a claim when smoke or soot has affected rooms that were not directly burned?
So, when it comes to smoke and soot-type damage, it can be pretty contentious because the insurance companies will sometimes take the position that, well, even though you can smell it in certain rooms or it’s in the HVAC system, and it’s spread throughout the home or the business, that shouldn’t be covered.
But it’s not a very black-and-white type of issue because the way these policy coverages are defined is physical loss. They cover physical loss to the property, so that means damage to the property, like soot damage, is damage to the property. It’s something that is a real thing.
It affects the property. It’s actually a part of the claim. It’s part of the dwelling damage, and it should be covered, but that is often a fight that insurance companies will want to have.
What evidence can support the need for professional cleaning, odor treatment, or replacement of contaminated materials?
“So often, with smoke and soot that spreads through the HVAC systems and properties, you’ll need to hire an expert to prove that type of damage. The insurance company will likely hire their own expert for something like that. So, when we’re dealing with those kinds of claims, as I said before, it’s not as straightforward because sometimes you can’t see the damage, but you can smell it, for example. So, you will need an expert to prove that.”
What options does a homeowner have if the insurer approves surface cleaning, but a qualified professional recommends more extensive work? For example, if smoke odors or contamination remain after the approved cleaning, how should the homeowner document and raise that issue?
If there’s still smoke or soot damage and you know it’s there, it’s in the HVAC system example and you can smell it, and it’s spread throughout the property, that’s often the type of damage that insurance companies will push back on paying for.
And if they’re not willing to pay for that, which they often aren’t, you’ll need to retain an attorney to fight that. And what the attorney will do is hire an expert, which is typically a certified industrial hygienist, who will come in and establish, through their scientific methods, the presence of the smoke and soot and the other residue, which often take the form of toxic chemicals, and prove that it is actually affecting parts of the home, and the insurance company needs to pay to clean that up
Texas Bad Faith Insurance Lawyer
We’ll Go Beyond to Get You Back
Get Compensated For Your Injuries & Damages! Call Us For A FREE Case Review. Call Us For A FREE & Confidential Case Review Today!Rebuilding the Property and Repairing its Systems
What do you examine when an insurer’s repair estimate is significantly lower than the contractor’s estimate?
So, in terms of repair costs, oftentimes there will be some disagreement between the contractor and the insurance adjuster about how much something costs to repair and the charges that the contractor is putting into their estimate.
Typically, the way that gets resolved is the contractor and the insurance company communicate and come up with some kind of compromise. So, the contractor knows, “Okay, I’m gonna do this work, and the insurance company is going to pay X for it.”
There are times where the contractor will be brought in, do repairs, then their actual invoices get submitted to the insurance company, and the insurance company balks at it or says, “We’re not gonna pay $100,000, but we’ll pay $70,000.”
Then that ends up being a situation where you might have to get an attorney involved to bridge that gap to get enough money from the insurance company to cover all of the repair costs.
How should homeowners handle additional damage discovered after walls, floors, or ceilings are opened?
So, homeowners often will find additional damage when their homes are being repaired because the contractors will start tearing out walls and then, for example, they’ll find the wood behind the walls has rotted or something from being exposed to water. They can discover other things as well.
What typically happens there is the contractor will need to document that hidden damage, and then update their repair estimate to reflect the cost of fixing that additional damage, which they would submit to the insurance company as what’s called a supplemental claim.
The insurance company then will have the ability either to pay for the additional damage, or sometimes they will make arguments that the additional damage is unrelated, and there can be a dispute in that situation. So, it really just depends on that scenario whether the insurance company will accept the supplemental claim or not.
How can policy terms affect payment for building code upgrades required during reconstruction?
So, if there are building upgrades that are required, for example, sometimes homes have to be raised for certain type of water damage or flood claims, or if they’re just code upgrades that the city requires, there’s usually coverage in an insurance policy for that code upgrade.
It’s usually some sort of sub-limit of the policy limit for the dwelling. So, I’ve seen policies where for code upgrades there’s $30,000 in coverage or $50,000. But that usually is in policies to pay for things that the city or county requires.
What documentation helps establish that electrical, plumbing, or HVAC damage resulted from the fire rather than an unrelated maintenance issue?
So typically, you would have the expert prepare a report. They will do certain tests that will establish that this type of damage is a result of the fire as opposed to some other cause
Selecting a Restoration Contractor
 From your experience handling disputed claims, what should homeowners look for when choosing a restoration company?
Well, just like any company, you want to do your research, and restoration companies are no different.
You want to get online and look to see what kind of reviews they have. Some of these restoration companies I’ve seen just completely overcharge people for the work that they do. So, if they’re doing that, that will often pop up in a Google review. Just do your research. Make sure you’re dealing with a reputable company. I also suggest, seeing if they’re a member of the Better Business Bureau.
Does a homeowner have to use the insurer’s recommended contractor, and what should they verify before making that decision?
A homeowner does not have to use the company that the insurance company is recommending.
Sometimes it is beneficial to do that just because the insurance company’s recommending them, so they’re more likely to pay them than if you go out and hire your own contractor that they don’t know. But you certainly are entitled to hire whoever you want. I would just recommend that whoever you hire to do the repairs, make sure that they are bonded and licensed and do your research online to see what kind of reviews they have.
But you absolutely have the right to hire your own contractor.
What contract terms should homeowners understand before authorizing work, particularly payment obligations and any transfer of insurance rights?
I think the best thing to do is to just enter into a contract with your contractor that’s their normal contract and not something that’s contingent on the insurance company paying.
There’s different ways that they can agree for the contractor that they select to be paid. One is they just do a traditional contract that says, “You do this amount of work, and we’ll pay you.”
But there’s other contracts that I’ve seen where insureds will agree with the contractor that they will only pay them based on what the insurance company pays out. And so, in those types of contracts, the contractor says, “We’ll agree to be paid based on what the insurance company agrees they owe.”
And they will get some sort of assignment from the client that says, “Any insurance money that you’re paid on the dwelling part of the claim, you’re assigning to us.”
So, there’s just different ways that people, uh, different agreements people get into with their contractors. We typically don’t get involved in that.
We just focus on getting the insurance company to pay what they owe under the policy.
Insurance Payments and Restoration Expenses
What can homeowners do if they need funds for emergency work or temporary housing while the claim is still being evaluated?
ALE coverage is something that the insurance companies will start to pay pretty soon after the claim is filed because the whole point of it is to be able to get people into replacement housing. So that will be paid up until the repairs are done to the extent the people can move back in their home, or the policy limits are reached.
So, if they’ve paid it for several months or a year, and they hit the policy limit on that particular coverage, even if the home is not fixed to the point where people can move back in, that’s all they have to pay. It’s up to the policy limit. But that’s what that coverage is for.
How should homeowners respond when an insurer’s payment does not cover the documented restoration costs?
So, in terms of repair costs, oftentimes there will be some disagreement between the contractor and the insurance adjuster about how much something costs to repair and the charges that the contractor is putting into their estimate.
Typically, the way that gets resolved is the contractor and the insurance company communicate and come up with some kind of compromise. If that doesn’t happen then that ends up being a situation where you might have to get an attorney involved to bridge that gap.
What deadlines or policy conditions should homeowners understand before accepting payment, completing repairs, or challenging the insurer’s decision?
The main deadline that homeowners need to be aware of is, in Texas, you have two years, typically to file a lawsuit.
I always advise people, if there’s still a dispute with the insurance company, not to wait more than two years after the date of loss to file a lawsuit. Now, that period gets extended because it technically doesn’t run until the parties reach an impasse. So the insurance company says, “We’re not paying you anymore,” or they deny the claim. If they deny the claim, that will start the clock. But just to be on the safe side, I tell people to file a lawsuit within two years.
Injured in an Accident?
We’ll Go Beyond to Get You Back
Get Compensated For Your Injuries & Damages! Call Us For A FREE Case Review. Call Us For A FREE & Confidential Case Review Today!Common Homeowner Questions
What is the most common mistake homeowners make during restoration that later complicates their insurance claim?
Yeah, the most common mistake homeowners make during the restoration process is they don’t document their losses, and what I’m talking about is their content. They start throwing stuff away before they’ve taken pictures or videoed it and before the insurance company has had the opportunity to send somebody out there to document the damage to the content and to take their own pictures.
What should someone do if their temporary housing benefits run out before repairs are complete?
ALE coverage is something that the insurance companies start to pay pretty soon after the claim is filed because the whole point of it is to be able to get people into replacement housing. That will be paid up until the repairs are done to the extent the people can move back in their home, or the policy limits are reached.
However, if they’ve paid it and they hit the policy limit on that particular coverage, even if the home is not fixed to the point where people can move back in, that’s all they have to pay. It’s up to the policy limit.
What distinguishes a legitimate disagreement over coverage or repair costs from potential insurance bad faith?
A legitimate disagreement over repair costs involves things like the contractor wanting to potentially install something that could be considered an upgrade, for example.
So, they’re replacing a certain type of countertop with a marble countertop, and the insurance company comes back and says, “We’ll pay to replace the countertop, but we’re not going to pay for a much more expensive material here.”
It’s pretty typical that there’s disagreements between the contractor and the insurance company during the claim process, but they’re usually able to work those things out.
And if they can’t work them out, and there’s a disagreement about the scope of the repairs or the cost, then every insurance policy has an appraisal clause that can be invoked, and that’s typically what it’s there for. It can be invoked by the insured or the insurance company, where basically two sides select an appraiser, they look at it, and they see if they can get an agreement on the scope of the repairs and the cost.
And then if they can’t, they select an umpire who becomes like a judge, and the umpire decides what the scope of the loss is and how much it’s going to cost. So, that’s pretty typical in an insurance claim. We get disagreements between the adjuster and the contractor on the cost or scope of damage.
What distinguishes that from a potential bad faith denial, for example, is when the insurance company knows something is covered, but they deny the claim.
I’ll give you an example from a recent case of mine. We had a homeowner who sustained a lot of damage from the freeze we had back in 2021. The adjuster was telling the condo owner that they needed to make the claim for the damage to the inside of the condo to their HOA insurance, which anybody who’s done any insurance work with condos knows that the HOA insurance only covers the common areas.
Everything from the walls in a condo, you have to get condo insurance for that. And my client had condo insurance, and the adjuster was telling her for months, “Go make the claim with your HOA.”
So, that potentially could be bad faith, especially if the adjuster is told multiple times by the HOA representatives and their insurance that, “No, we don’t cover the condo damage. We only cover the common areas.”
But the adjuster in my case continued to deny the claim. So, that’s an example of a potential bad faith situation where they wrongly deny coverage when they know or should know better
What warning signs suggest a homeowner should consult a lawyer while restoration is still underway?
I’ve had situations where contractors have wanted to get paid even though the insurance company has not agreed to pay for certain things that they did, and that can create some issues.
Ultimately, the contractor and the client have a deal between themselves. And what we do is we try to get as much money as we can from the insurance company that we can justify based on the coverage and the damages. So, we typically don’t get involved too much in the disputes between the client and the contractor ’cause that’s not what they hire us for.
They hire us to go after the insurance company.
How does your firm work with contractors, engineers, or other experts to evaluate a disputed fire loss?
Yeah, so if there’s a dispute on a fire claim, either in regard to coverage or the amount of the loss, we will retain a contractor to go do a full scope of damage. We will also retain an engineer, if there’s a dispute as to how the fire started or sometimes, we need the engineer to chime in on certain aspects of the repairs.
We will pay the cost of the experts. We may even need a fire expert, a cause and origin expert if there’s some dispute as to how the fire started or if arson was involved. We hire all those experts, and then we use them to pursue a full recovery for our client.
And then at the end of the case, we get reimbursed for those costs out of the recovery, plus our attorney’s fees. And then what’s left over from that will go to the client
What should homeowners bring to their first consultation, and what can your team help them understand at that stage?
“Yeah, typically on the first consultation, we want to see the correspondence from the insurance company, so we know what the insurance company’s position is.
We want to see the policy, to look at the coverages and exclusions and the amounts of coverage. Typically, if they have some estimates from contractors, regarding repair costs and things like that, we like to see that as well. Usually, some pictures of the damage I also like to see to provide some context on how serious the damage is and the claim is.”